Category: Finance Page 2 of 3

The Good and Bad Side of Loans for Small Business Owners (And How to Know If You’re Ready)

Should you take a loan as a small business owner? We’ve seen businesses take a loan and turn it into their breakthrough moment, the money that changed everything, opened doors, and scaled them faster than they ever imagined. But we’ve also seen loans destroy businesses, drain entrepreneurs emotionally, and wipe out years of hard work because the debt became bigger than the dream. So, what’s it about small business loans? 

We need to understand that money is powerful. And a loan can be a ladder or a trap. And in today’s economy, where entrepreneurs are facing rising costs, unpredictable demand, and tight cashflow cycles, the topic of small business loans is more relevant than ever.

This blog breaks it all down, the good, the bad, the dangerous, the smart, with real examples, expert advice, and mistakes founders often make when borrowing money.

What Exactly Is a Loan? 

According to the Corporate Finance Institute (CFI), a loan is a form of debt in which one party lends money to another with the expectation that it will be repaid, usually with interest, over a defined period.

In simple terms, a loan is money you borrow today to use for growth, stability, or opportunity, and return later under agreed conditions. It is one of the oldest financial tools used to power businesses, from small shops to global corporations like Walmart, Tesla, and Starbucks.
The Good Side of Loans for Small Business Owners

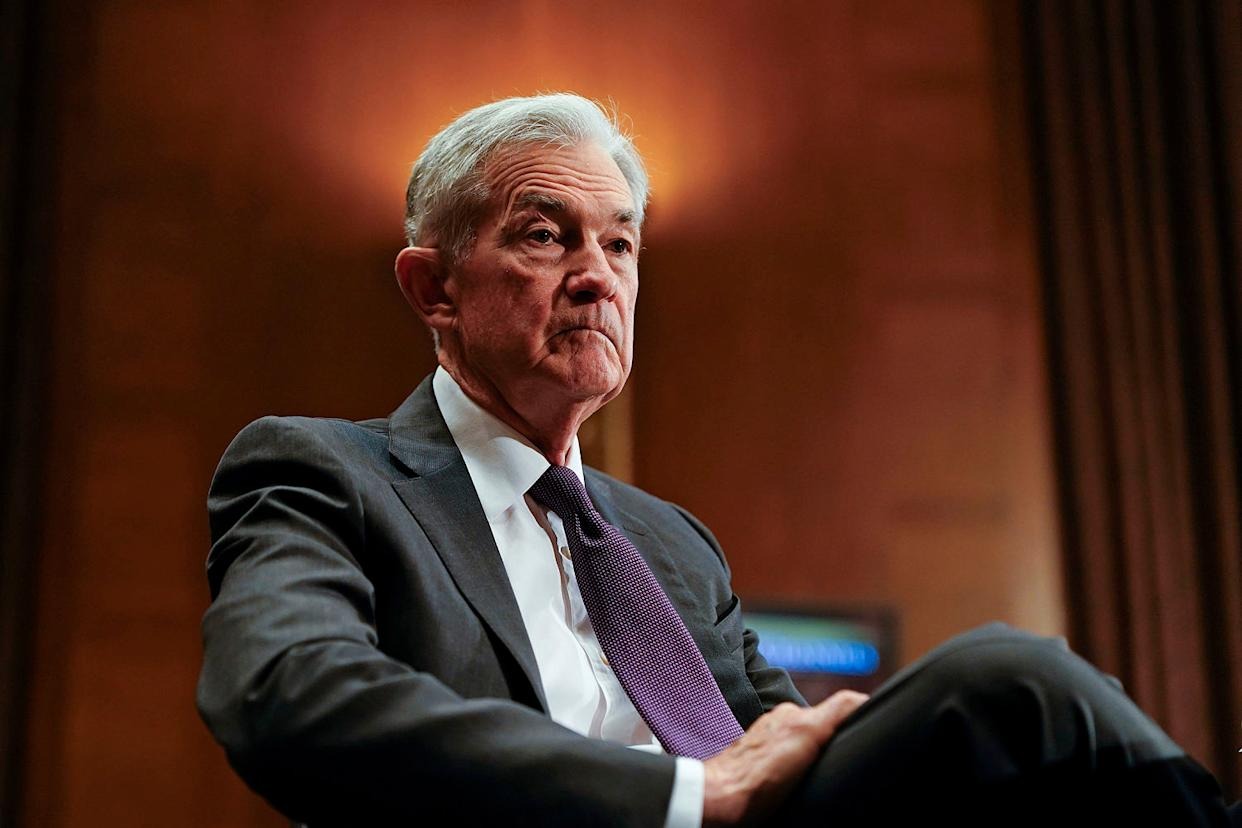
Understanding the Role of the Fed Chair and Speculations Around Powell’s Replacement. 

In the last post, we addressed the concept of the Fed Chair and the speculation about a new One. Is Trump really going to exercise his authority and start a serious battle based on his monetary differences with the Fed Chair? We also looked at the possible candidates for this office and what each of them brings to the table. But in today’s blog, we will examine in detail the job of the Fed Chair and whether the speculation about his office is valid.

Will Trump Announce a New Fed Chair before Christmas, Speculation or fact?

What Does the Fed Chair Do?

In the US, the Fed Chair’s office is one of the most influential positions in global finance. A decision from the FED chair can literally send the stock market booming or bleeding. The FED chair has a number of  Responsibilities, some of which are:

  • Setting the FOMC agenda: determining which monetary policies are prioritised.
  • Guiding interest rate decisions, impacting borrowing, lending, and investment.
  • Dual mandate oversight: balancing inflation control with employment aims.
  • Global representation entails participation in international economic negotiations.

The Fed’s power is distributed among its twelve voting members; however, the chair sets the tone and agenda, making their role critical in influencing economic policy.

How Powell Has Affected the Markets (Including Crypto)

Stop Guessing: Top Financial Ratios Formulas for Entrepreneurs in 2026

What are Financial Ratios?

Financial ratios formulas for entrepreneurs are numbers that tell you the truth about your business’s financial health. They are mathematical comparisons that show how healthy your company really is over a specific period. Instead of guessing, these ratios help you see whether your business is growing, struggling, or just stagnant.

They also allow you to measure your performance against competitors in your industry. With the proper ratios, you can tell if you’re ahead, behind, or right on track. In simple terms, financial ratios help you understand your business’s strengths, weaknesses, efficiency, and overall financial position at a glance.

Why should you know Financial Ratios/Formulas?

Because I watch a lot of business shows and investor pitches, one thing has become very clear: when you sit in front of an investor asking for funding, there are a few things they immediately want to understand:

  1. What your business or idea is about
  2. Who you are as a founder or team
  3. What your numbers are saying

And of all three, I’ve noticed something interesting: investors will argue with you about your idea, they may even question your personality, but the moment you start talking numbers, the entire conversation changes.

In fact, the only reason an investor would walk away from a business with significant numbers is a lack of integrity on the part of the entrepreneur. But with substantial numbers, even a “not-so-brilliant” business idea can get praise and, many times, even funding.

The Double-Edged Sword of Leveraging: Success or Disaster

Part 3: Pros and Cons of Financial Leveraging. 

Why Leverage Is a Double-Edged Sword

Financial leverage is powerful. It can help a business grow faster or destroy it just as quickly.

When used wisely, it allows entrepreneurs to multiply profits, expand operations, and fund new projects without relying solely on their savings. But when used recklessly, it can lead to overwhelming debt, bankruptcy, and loss of control.

That’s why financial leverage is called a double-edged sword. It can cut both ways.

In this final part of our series, we’ll explore how to use leverage safely, understand its types, and know when to stop borrowing before it’s too late.

Part 1:The Foundation of Financial Leverage: How Borrowing Builds Wealth

Part 2: The Simple Maths of Financial Leveraging: Ratios, Measures, and the Analysis.

The Upside of Financial Leverage

Let’s start with the positives. When used correctly, leverage can unlock amazing opportunities for growth.

1. Faster Expansion
Small businesses often lack the funds to grow quickly. Borrowing gives them a chance to open new branches, buy better tools, or hire more workers — actions that increase profits over time.

2. Higher Returns on Equity
Leverage allows you to earn higher returns with less of your own money. If your project generates a higher return than your loan interest rate, you come out ahead.

3. Access to Bigger Opportunities
Some investments,  like real estate, manufacturing, or large-scale imports, require significant upfront capital. Leverage opens the door to these markets.

4. Tax Advantages
In many countries, interest paid on business loans is tax-deductible. This means you can reduce your tax burden while investing in growth.

The Downside: Borrowing Becomes a Burden

The Foundation of Financial Leverage: How Borrowing Builds Wealth

Part 1: How Borrowing Can Build Wealth

What Is Financial Leverage?

Financial leverage is taking advantage of borrowed funds to grow wealth or expand a business. In simple terms, it means using other people’s money to do more than you could with your own.

When a company or an individual borrows money to buy an asset or invest in a project, they are using leverage. The goal is to make more profit from that investment than the cost of borrowing.

For example, a business that borrows $1 million at 8% interest and uses the funds to build a new product line expects the profit from that expansion to exceed $80,000 in interest costs. If that happens, leverage worked.

Why Leverage Matters in Business

Without leverage, most businesses would grow slowly. Borrowing allows entrepreneurs to access bigger opportunities without waiting years to save the full amount.

Leverage can:

  • Help businesses expand operations faster.
  • Allow individuals to invest in income-producing assets.
  • Multiply returns when the investment performs well.
  • Increase a company’s total value through smart debt use.

However, leverage is a double-edged sword. It increases both profits and losses. When things go wrong, the same loan that made growth possible can become a heavy burden.

How Financial Leverage Works

Emergency Funds: Simple Tips to Build One

Someone said, “The moment I begin to save for rainy days, it starts to rain the next day”. This is a hilarious way to describe the situation that many of us find ourselves in. We plan to save money for the future, only to discover that it’s almost impossible. We have spent more than we can afford and would need to dip into the other account to pay. Some would even borrow against the maturity of our savings account. Hence, it ends up as though we have not saved anything at all. 

The primary reason for this is that most people save up without a strategy. An excellent saving strategy takes your savings and apportions it into very strategic portfolios. An emergency portfolio is something you should aim to have as soon as you begin to experience financial stability. 

For most readers, an emergency fund portfolio is like preparing for a bad day. It conveys the impression that they are wishing themselves bad luck. The opposite is the case. An emergency fund account is not to be seen as a pot of bad luck waiting to manifest. It should rather be seen as a haven for financial inconsistencies or required expenses that were not planned for. In fact, it could be a portfolio that helps you harness opportunities in the future. 

What is An Emergency Fund?

An emergency fund, in simple words, is money set aside to cover unexpected expenses during periods of personal financial distress. Situations such as job loss, illness, a recession, or sudden medical bills are examples of when an emergency fund can become essential.

The primary purpose of this fund is to provide a financial safety net during unforeseen circumstances, helping you meet urgent expenses without resorting to high-interest debt or dipping into your strategic savings. By doing so, you reduce financial stress and keep your long-term plans intact.

The 4 Levels of Wealth: How to Move from Stability to Financial Freedom

Wealth is a holistic statement, and it does not only refer to financial stability. Of what good is money if the people you love the most have no connection with you or just hate you for what you have become? However, in this blog post, we will explore very briefly the four levels of financial wealth and the way to get to each of the levels. The tips in this blog will help you identify your level and scale up as quickly as possible at each level. 

Romance to Riches: Navigating Love and Debt in 2025

1. Stable Level 

Building a Solid Financial Foundation

The first level, financial stability, aims to ensure you can survive with peace of mind. It is at this level that you are able to start saving and accumulate enough to be able to survive job loss, have a financial buffer, and never borrow for emergencies or rent. At this level, you are able to stay afloat in the month, and then, from your accumulated savings, are able to handle any emergency that is within a certain threshold. 

This level is where you can start talking about financial security and control. You’ve moved beyond living paycheck to paycheck and are now beginning to build a structured and reliable financial stack. 

How to Get to the Stable Level

  • Get your income to match your expenses
  • Avoid high-interest debts
  • Live below your means and track every expense
  • Build an emergency fund covering at least 6 months of expenses
  • Get health and life insurance.

The fantastic thing about financial stability is that it allows you to focus on growth rather than survival. It’s not about luxury yet; it’s about breathing space and confidence.

Romance to Riches: Navigating Love and Debt in 2025

Dealing with Debt as a couple

Financial friction in romantic relationships can be a significant challenge, but it’s also an opportunity for growth and understanding. As many couples navigate the emotional depths of love, they also face practical matters like managing debts—student loans, credit cards, and mortgages—that could weigh heavily on their shared future. In 2025, the dream remains the same—a love that blossoms into abundance and happiness. With wise debt management and open communication, couples can overcome financial stresses, strengthening their bond and turning their shared dream into a beautiful reality. 

I often watch business shows and talks, and it’s amazing how complex our world is running now. It’s built with only money in mind as though money is the most important thing in life. Love is more important than money, so why let poor financial decisions ruin the most beautiful aspect of your life? Let’s consider a few steps you can take as a couple to reduce financial friction in your relationship. 

Romance to Riches: Practical strategies for Couples looking to Build Wealth in 2025.

<a href="https://www.freepik.com/free-photo/impressed-adult-couple-wearing-sunglasses-holding-money-man-looking-side-woman-keeping-hand-air-looking_12860626.htm#fromView=search&page=1&position=26&uuid=f4b3b2d5-a8e4-4307-a925-856832b7aec8&query=romance+and+money">Image by stockking on Freepik</a>

Love is beautiful, but it becomes even more gorgeous when done correctly. That has been the goal of the Romance to Riches series I have been guiding us through. Thought by thought, I have examined the possibilities for lovers to start on the proper financial footing before they even say I do. The decision to begin correctly not only reinforces their love but also strengthens it by ensuring their marriage is built on solid financial ground.

In the second part, we also examined the concept of prenuptial agreements and their role in marriages in this decade. We explored the myths and facts about prenups. For many readers, prenuptial agreements (prenups) seem like a matter reserved for wealthy individuals, such as football players and entertainers, who want to protect their estates. However, the last blog post debunked these myths and revealed the crucial facts about prenuptial agreements, who can benefit from them, and what advantages proper planning offers.

Want to catch up with the last two articles? Here are their links:
Romance to Riches: A Couple’s Guide to Starting a Family Investment

Romance to Riches: Are Prenups a Smart Move for Couples in 2025?

Should the Path to the CEO’s Office Be Through Engineering and Design?

“The path to the CEO’s office should not be through the CFO’s office, and it should not be through the marketing department. It needs to be through engineering and design.” – Elon Musk

What makes engineers and product designers better suited for the CEO’s office? When Elon Musk made this statement, he wasn’t trying to disrespect the finance or marketing department. Instead, he was saying that the strongest companies are led by people who deeply understand the product, how it’s built and how people will use it. 

But when the person at the top doesn’t have a deep understanding of these things from product, innovation, and design, the company risks losing its core identity, which is why some companies go into bankruptcy, abrupt closing of business, customers losing interest and many more.

A report by Harvard Business Review points out that CEOs with technical backgrounds are often better equipped to drive long-term innovation because they understand the “how” behind the products, not just the “how much.”

But what does this mean? This blog post will give you a comprehensive understanding of this.

1. What’s Wrong With the CFO Route?

The CFO (Chief Financial Officer) is the money manager of a company. Their job is to balance the books, control costs, and ensure the company remains financially healthy.

That’s vital, but if a CEO only thinks like a CFO, they may focus too much on cutting expenses instead of creating new opportunities.

See how Nokia, which once dominated the phone market, but focused more on profits than innovation. Apple, meanwhile, poured money into design and user experience, and we all know how that turned out.

2. What’s Wrong With the Marketing Route?

Page 2 of 3

Theme by Anders Norén & Customized by Karol K