Category: entrepreneurship Page 1 of 10

Employees Missing Deadlines? 5 Ways Managers Can Fix Poor Communication

Are your employees constantly missing deadlines? The problem may not be laziness. Poor communication and a lack of trust could be affecting your team’s performance.

A business can have talented employees and still struggle to get work done on time. Projects get delayed. Customers become frustrated. Managers spend more time following up. Employees blame one another, and the same problems keep happening.

One common reason is poor communication in the workplace.

This issue was a major assignment in one of my MBA classes: how do we fix communication issues as a manager?  The question was simple:

Imagine you are a manager, and your team is missing deadlines because employees are not communicating well with each other. What is the main problem, and what steps would you take to solve it?

At first, the obvious answer might be poor communication. However, poor communication can be a symptom of a deeper problem and in many teams, that deeper problem is a lack of trust.

Why Are Employees Missing Deadlines?

Missing a deadline does not always indicate that an employee is irresponsible. Often, an employee may lack the necessary information to complete the task, misunderstand another team member’s expectations, notice a problem but hesitate to report it, or assume someone else is handling part of the work. Therefore, managers should look beyond the missed deadline and ask the right questions to understand the underlying reasons.

The big question a manager should ask is this: Why did the communication fail?

Several factors can contribute to poor communication within a team, and in today’s article, I will help you identify 5 major causes of poor communication in the workplace and how to address each one. 


5 Major Causes of Poor Communication in the Workplace


1. Lack of Clarity

Employees need to understand what they are expected to do. Without clarity, communication is ineffective. Clarity is not what you think you said; it is rather what the person understands you to have said. That means you might need to be more specific about what you are trying to communicate, especially when you are working with a team that is not used to seeing your work. 

If a manager says, “Get this done quickly,” different employees may interpret “quickly” differently.

A good manager should clearly communicate:

  • What needs to be done
  • Who is responsible
  • When it should be completed
  • What standard is expected
  • What resources are available

Clear expectations reduce unnecessary confusion.

2. Poor Listening Skills

Communication is not only about speaking; it is also about listening. An employee may receive instructions but fail to understand them because they were distracted or did not ask questions. That is why every manager must be patient enough to troubleshoot conversations with their staff. Encourage them to give instant feedback on what they heard you say. 

A simple question such as “Can you repeat what you understand the task to be?” can prevent major mistakes.


3. Lack of confidence.

This is where the situation worsens. Employees who do not trust their management or coworkers may be more reluctant to speak out or share information. For example, an employee may see that a project will miss its deadline.

Instead of informing the management, the employee may remain silent because they are terrified of being chastised.

By the time the manager finds out, it may be too late to solve the situation. Trust allows workers to say things like:

“I have difficulty with this work. “I need help.” This type of talk may rescue a project. 

4. Inappropriate Communication Channels

Not every message should be communicated through the same channel.

Some businesses depend heavily on WhatsApp groups. Others use email, Slack, Microsoft Teams, project-management software, or face-to-face meetings.

The problem is not necessarily the platform. What matters is that businesses establish clear communication channels for different types of information.

For example:

  • Urgent issues → phone call or direct message
  • Formal instructions → email or documented platform
  • Team updates → team communication channel
  • Complex issues → meeting or video call

Also, I see some businesses with a mandatory rule that staff must communicate only through certain platforms. While this is necessary in many sensitive departments, for most day-to-day work, managers should encourage direct communication to reduce the bureaucratic feel. 

5. Different Communication Styles

Individuals communicate differently. One employee may prefer direct teaching. Another may require further explanation. Some staff talk openly in meetings, while others prefer to share their views discreetly.

Managers must comprehend these distinctions. Good leadership doesn’t require everyone to communicate the same way. It means creating a setting where everyone can communicate successfully.

How to Build a Startup in 2026: 6 Lessons Every Founder Should Know

The Real Problem May Be Trust

How to Build a Startup in 2026: 6 Lessons Every Founder Should Know
How to Build a Startup in 2026

Every year, thousands of founders launch startups believing that a great idea is all they need, even the news of how much startups founders are raising is always shocking and people often wonder how to build a Startup in 2026? Yet research consistently shows that most startups don’t fail because founders lack passion. 

Over the past few weeks, I’ve found myself spending a lot of time studying successful startup founders and how to build a Startup in 2026. After writing about the business lessons from Iyinoluwa Aboyeji, co-founder of Andela and Flutterwave, I kept noticing the same patterns. The six lessons below appeared repeatedly, whether I was reading about Airbnb, Canva, Stripe, Andela, or listening to startup investors explain why they back one company instead of another. 

If you’re wondering how to build a startup in 2026, the first thing you need to understand is this: not every new business is a startup.

A startup is built for rapid growth. Paul Graham, co-founder of Y Combinator, famously described a startup as “a company designed to grow fast.” Growth isn’t just something that happens later; it’s built into the company’s vision from the very beginning.

Whether you’re developing a technology platform, launching an online marketplace, building a fintech company, or creating a new software product, the principles are the same. Before you think about funding, marketing, or scaling, you need to understand what makes a startup capable of growing quickly.

If you’re serious about learning how to build a startup in 2026, these are the principles worth paying attention to. 

Table of Contents

  • What Makes a Startup Different From a Small Business?
  • Lesson 1: Solve a Problem Worth Paying For
  • Lesson 2: Build for Scale from Day One
  • Lesson 3: Stop Building AI Products Nobody Needs
  • Lesson 4: Build a Team That Can Grow Without You
  • Lesson 5: Your First Customers Matter More Than Investors
  • Lesson 6: Never Stop Learning
  • Frequently Asked Questions

1. How to Build a Startup in 2026 Starts with Solving the Right Problem

Imagery from Canva geralt 

If there’s one lesson every aspiring founder should understand before building a startup in 2026, it’s this “great startups don’t begin with products, they begin with identifying problems.”

One of the biggest misconceptions about startups is that all you need is a brilliant idea. In reality, investors, accelerators, and successful founders rarely get excited about ideas alone. They’re interested in businesses that solve meaningful problems for a large number of people.

Paul Graham, co-founder of Y Combinator, famously summed it up in just four words: “Make something people want.” It sounds simple, but those four words have shaped thousands of successful startups around the world.

As I was writing my previous article on the business lessons from Iyinoluwa Aboyeji, one thing became obvious. Whether you’re looking at Flutterwave, Andela, Airbnb, Canva, or Stripe, these companies didn’t become successful because they had clever ideas. They succeeded because they identified problems that millions of people were already experiencing.

Before you think about building an app or designing a product, ask yourself a few important questions.

  • What problem am I solving?
  • Who experiences this problem?
  • How are they solving it today?
  • Why would they choose my solution instead?

These questions may seem basic, but they form the foundation of every successful startup. A framework could look like this  Problem to Solution and Strategy.

First, clearly define the problem and understand who is affected by it. Then explain how your solution improves on what’s already available. Finally, think about your strategy. 

  • How will customers discover your product? 
  • What makes your solution different? 
  • Why should they trust you?

The truth is, a startup without demand is simply a project. That’s why successful founders spend time talking to potential customers before spending months building products. They validate demand, collect feedback, and improve their ideas based on real conversations rather than assumptions.

8 Powerful Business Lessons from Iyinoluwa Aboyeji

When people talk about African entrepreneurship, names like Aliko Dangote and Tony Elumelu often dominate the conversation. However, as a young person, one would also love to hear some of the most valuable business lessons from Iyinoluwa Aboyeji, which may be just as important for today’s entrepreneurs. 

Over the past decade, Aboyeji has quietly helped change how the world views African innovation, becoming one of the most influential startup founders on the continent. 

Before the age of 30, he had already co-founded Andela and Flutterwave, two startups that later achieved unicorn status, a term used for privately held companies valued at more than $1 billion. Today, through Future Africa, he continues to invest in and mentor founders building the next generation of African businesses.

Recently, while watching his interview on The School of Hard Knocks, one thing stood out.

He didn’t spend time talking about becoming rich or about himself or his worth. Instead, he spoke about systems.

  • People.
  • Trust.
  • Service.
  • Long-term thinking.

The more I listened, the more I realised these weren’t just lessons for startup founders looking to build unicorns. They’re lessons every entrepreneur can apply, whether you own a restaurant, run a fashion brand, manage a farm, freelance online, or are building your first business.

So, I did my diligent research, read articles, books, and almost everything I could learn and hear from him too. Below are the biggest business lessons I believe every entrepreneur can learn from Iyinoluwa Aboyeji.

1. Solve Big Problems, Not Small Opportunities

One thing I admire about Iyinoluwa Aboyeji is that he never talks about building unicorns as though that should be the goal.

In several interviews, he has said entrepreneurs should focus on building great businesses and solving real problems. The valuation comes later.

That mindset helps explain the success of companies like Andela and Flutterwave. Andela addressed the challenge of connecting African software talent with global opportunities, while Flutterwave simplified payments across Africa. Both companies focused on problems affecting millions of people.

Many entrepreneurs start with the question “What business can make me money?”

But successful founders often ask “What problem needs solving?” The difference may seem small, but it changes everything.

If you’re still searching for a profitable business idea, you may enjoy our guide How to Validate a Business Idea Before Investing Your Money. 

2. Businesses Scale Through Systems, Not Hustle

One of the most interesting moments from the interview came when Iyinoluwa Aboyeji was asked about the secret to building billion-dollar companies.

Many people expect successful founders to talk about working longer hours, sacrificing sleep, or grinding harder than everyone else.

Instead, he pointed to something much more important: “Systems.” This stood out because we live in a culture that glorifies hustle. Everywhere you look, entrepreneurs are being told to wake up earlier, work harder, and keep pushing.

Hard work matters, but hard work alone doesn’t create a scalable business.

Think about it this way. If your business cannot function without you answering every call, approving every payment, solving every problem, and making every decision, then your business is not really growing. It is simply becoming more dependent on you.

That’s why many entrepreneurs end up trapped in the businesses they created.

Successful companies grow because they build systems that allow work to happen consistently. They create processes for customer service, sales, operations, hiring, and communication so the business can continue to run even when the founder steps away.

This is one of the reasons franchises like McDonald’s can operate thousands of locations around the world. Their success isn’t built on finding extraordinary people in every city. It’s built on systems that produce consistent results.

How to Calculate True Business Profit: 9 Costs Most Entrepreneurs Forget

Calculate True Business Profit

How do you know if your business is truly profitable? Let’s put it another way: Do you know how to calculate your true business profit?

Many entrepreneurs assume that if money is coming in, the business must be making a profit. A freelancer lands a $1,000 project and immediately starts planning how to spend the money. A retailer records $5,000 in sales and celebrates a successful month. A Catfish farmer sells an entire harvest and assumes the business is thriving.

But revenue and profit are not the same thing.

Revenue is the total amount of money your business generates. Profit is what remains after all business expenses have been paid. The challenge is that many entrepreneurs forget to include certain costs when calculating profitability. As a result, they often believe they are making more money than they actually are.

This is why some businesses appear successful on the surface yet struggle financially behind the scenes. Sales may be growing, customers may be buying, and money may be flowing into the business, but hidden expenses can quietly erode profits.

As Warren Buffett famously said, “Revenue is vanity, profit is sanity, but cash is king.“

If you want to calculate your true business profit, there are several important costs you need to account for first. In this blog, we’ll explore nine commonly overlooked expenses that can significantly affect your bottom line and help you determine whether your business is genuinely profitable.

1. The Actual Cost of Producing Your Product or Service 

Many entrepreneurs underestimate the true cost of producing and delivering their products or services. When calculating business profit, production costs are one of the first expenses you must account for because they directly affect your bottom line.

If you bake cakes, your costs are not limited to flour and sugar. You also need to consider eggs, butter, packaging, electricity, gas, delivery materials, and even the wear and tear on your equipment.

If you’re a freelance writer, your costs are not zero simply because you work from home. Internet subscriptions, writing tools, AI software, electricity, and professional development courses are all part of the cost of delivering your service.

If you’re a catfish farmer, your expenses go far beyond purchasing fingerlings. Feed, medication, pond maintenance, water management, labour, transportation, and mortality rates all contribute to your overall production cost.

The problem is that many entrepreneurs only count the obvious expenses while overlooking the smaller ones. Unfortunately, these seemingly insignificant costs accumulate over time and quietly eat into profit margins.

As management expert Peter Drucker famously said, “What gets measured gets managed.”

Meaning that if you don’t know your true production cost, you don’t know your true profit. Before you can confidently determine whether your business is profitable, you must first know exactly what it costs to create and deliver your product or service.

What Is Profit in Business? The Number That Tells You If Your Business Is Actually Working

How Nigerians in Diaspora Can Invest in Oil Palm Business in Nigeria (Without Farming Themselves).

How Nigerians in Diaspora Can Invest in Oil Palm Business in Nigeria

Nigeria consumes about 2.7 million metric tonnes of palm oil annually but produces only about 1.5 million metric tonnes. This leaves a supply gap of more than one million tonnes annually, requiring over $290 million in palm oil imports in 2024 alone.

Think about this for a moment: A country historically known for palm oil is now spending hundreds of millions of dollars to import a product it can produce itself. In the 1960s, Nigeria controlled almost 40% of the global palm oil market. Today, that figure has dropped to less than 2%, even as local demand from households, food processors, manufacturers, and export markets rises.

The Oil Palm opportunity has not disappeared

Nigeria’s fertile Palm Belt remains naturally suited for oil palm cultivation. The challenge has not been whether the land can produce, but rather issues such as poor seedlings, fragmented farming systems, underinvestment, and limited commercial-scale execution.

For investors, this raises an interesting question:

If Nigeria already has demand, suitable land, and a market that depends heavily on imports, could oil palm become one of the overlooked long-term investment opportunities of this decade?

Whether you live in Nigeria, the UK, Canada, the USA, or elsewhere in the diaspora, there are several ways to gain exposure to the oil palm value chain, from plantations and processing to partnerships and structured agricultural investments.

In this guide, we’ll explore the opportunities, startup costs, timelines, risks, and practical ways to enter Nigeria’s oil palm business wisely.

How to Start Investing in Oil Palm Production

For someone in the UK, Canada, or the United States saying, “I want to invest in oil palm. I have seen the market gap and think I can fill my share of the demand. But where do I start planting?” The answer may be simpler than many imagine.

In fact, it may be simple enough that you do not need to leave your location to participate in oil palm farming in Nigeria.

The standard path many take is to secure land, then hire a local manager to run the farm and send monthly reports. While this can work, it often leads to a steeper path to profitability and sustainability than expected. Managing an agricultural business remotely adds complexity: land verification, staffing, supervision, report quality, operational delays, and decision-making across locations and time zones.

For many diaspora investors, the challenge is not always access to capital; it is access to trusted execution.

That is why another route has increasingly gained attention: rather than building entirely from scratch, some investors choose to work with experienced, government-registered oil palm businesses and operators who already understand cultivation cycles, have existing systems, and know what it takes to run productive operations on the ground.

This does not remove the need for due diligence or eliminate risk, but it can reduce some of the early operational hurdles that discourage people from participating in agriculture from abroad.

How Towers Palm is Changing the Oil Palm Investment Space

What Is Profit in Business? The Number That Tells You If Your Business Is Actually Working

In our previous blog post, we wrote on one of the most talked-about numbers in entrepreneurship, “What Is Revenue in Business?” We said that Revenue tells us how much money a business generates from selling its products or services, and for many founders, it’s often the first sign that customers, investors, and even you, as a business owner, are paying attention. But revenue only tells part of the story. Hence, today we are focusing on Profit in business and everything about it. 

In fact, one of the biggest mistakes entrepreneurs make is assuming that high revenue automatically means a successful business.

I remember watching an episode of Shark Tank where an entrepreneur proudly announced that his company had generated hundreds of thousands of dollars in sales. The Sharks seemed impressed at first, but within seconds, the conversation shifted.

“What’s your profit margin?” “How much are you actually making?” “How much does it cost you to acquire a customer?” Suddenly, the room became quiet.

The startup’s founders, who were pitching, knew their revenue numbers perfectly, but it was a bit of a struggle to pin down exact figures for what the business was actually keeping after expenses.

And that’s an important lesson. In business, revenue might grab attention, but profit is what determines whether a business survives.

A company can generate millions in sales and still struggle financially. It can have customers, media attention, growing demand, and impressive revenue figures while quietly losing money every month.

History is filled with businesses that looked successful on the surface but eventually collapsed because they failed to turn revenue into profit.

That’s why understanding what profit in business is may be one of the most valuable financial lessons any entrepreneur can learn.

Because at the end of the day, businesses don’t survive on sales alone.

They survive on profit.

So, What Is Profit?

Simply put, profit is the money left after all business expenses have been deducted from revenue.

The formula looks simple: Profit = Revenue − Expenses

But despite how simple that formula appears, many entrepreneurs misunderstand what it means in practice.

Let’s imagine your business generates $20,000 in sales this month.

At first glance, you might feel like you’ve made $20,000. After all, that’s the amount that came into the business.

But then reality kicks in.

  • You paid suppliers.
  • You paid employees.
  • You spent money on marketing.
  • You paid for software subscriptions.
  • You covered transportation and operational expenses.

By the time everything is deducted, your numbers may look very different.

For example:

  • Inventory: $8,000
  • Salaries: $2,000
  • Marketing: $1,000
  • Transportation: $1,500
  • Software subscriptions: $500
  • Utilities and operations: $1,000

Total Expenses: $14,000

Actual Profit: $6,000

The business generated $20,000 in revenue but kept only $6,000.

And that difference is exactly why profit matters. Revenue tells you what came in, and Profit tells you what stayed.

In many ways, profit is the business world’s version of a report card. It reveals whether the business is truly creating value or simply moving money around.

This is one reason investors, accountants, lenders, and experienced entrepreneurs pay so much attention to profitability. Revenue may indicate that a company is attracting customers, but profit indicates whether the business model actually works.

As investor Warren Buffett has often demonstrated through his investments, great businesses are not necessarily the ones generating the most revenue. They are often the ones that consistently turn revenue into profit year after year.

The good news is that profit is not just a number you calculate. It’s also a skill you can improve.

Here are three profit-management skills every entrepreneur should learn.

1. Learn How to Control Costs Without Hurting Value

One of the fastest ways to improve your business’s profits is to learn how to manage costs wisely.

Notice I didn’t say “cut every expense.” Because many entrepreneurs hear the phrase “reduce costs” and immediately start removing things their business actually needs. They stop marketing, delay maintenance, reduce product quality, or underinvest in their team.

That often creates bigger problems later.

Instead, smart entrepreneurs focus on controlling unnecessary costs while protecting the things that create value for customers.

In his book Profit First, Mike Michalowicz explains that many businesses don’t have a sales problem; they have an expense problem. Money comes into the business, but poor spending habits prevent owners from seeing meaningful profits.

A simple question every entrepreneur should regularly ask is, “If I removed this expense tomorrow, would my customer notice?” If the answer is no, it may be worth reviewing.

5 Cashflow Tools To Track Business Health as a Sole Proprietor. 

In the first part of this series, we explored the AI skills every sole proprietor can learn to increase sales and 10X income. However, growing revenue is only one side of building a successful business. The other side is understanding your numbers. I have put together 5 Cashflow Tools To Track Business Health as a Sole Proprietor

Many businesses fail not because they lack customers, but because they lack financial understanding. (Survey: Half of US small businesses encounter fiscal challenges due to a lack of financial literacy, 2024)  

If you do not track your income, expenses, and profitability, it becomes difficult to scale sustainably. This is why having the right financial tools remains essential. The best platforms help you monitor your business health, control cash flow, and make smarter decisions that support lasting growth.

In today’s blog post, we will explore five powerful financial tools to help any sole proprietor manage their finances effectively.

1. Accounting Software to Track Income and Expenses

One of the most important tools for any business owner is accounting software. This type of software records all your financial dealings and helps you understand where your money is going.

Services like QuickBooks and Xero allow business owners to automatically track income, categorise expenses, and generate financial reports.

These tools are especially useful for sole proprietors because they simplify bookkeeping without requiring deep accounting knowledge. Instead of managing spreadsheets manually, you can see your financial position in real time.

Using accounting software helps you:

  • Track profit and loss accurately
  • Monitor business expenses
  • Prepare for tax season.
  • Understand whether your business is truly profitable.

When you clearly see your numbers, it becomes easier to determine areas where you can reduce costs or increase revenue.

2. Cash Flow Management Tools

Cash flow is the lifeline of any business. Even profitable firms can struggle if they do not manage when money comes in and goes out. (Cash Flow Management for Financial Stability: Profitability, Debt Service, and Projections, n.d.)

Cash flow tools help you predict and control financial movement inside your business. They show whether you will have enough funds to pay bills, invest in marketing, or hire help.

Tools such as Float and Pulse provide visual forecasts, making financial planning easier.

These tools allow you to:

  • Forecast future cash flow.
  • Identify likely financial gaps.
  • Plan investments more confidently.
  • Avoid monetary surprises

For sole proprietors looking to increase income, proper cash flow management guarantees your business can support growth.

Selling Beyond Amazon: Alternatives for Creators and Businesses

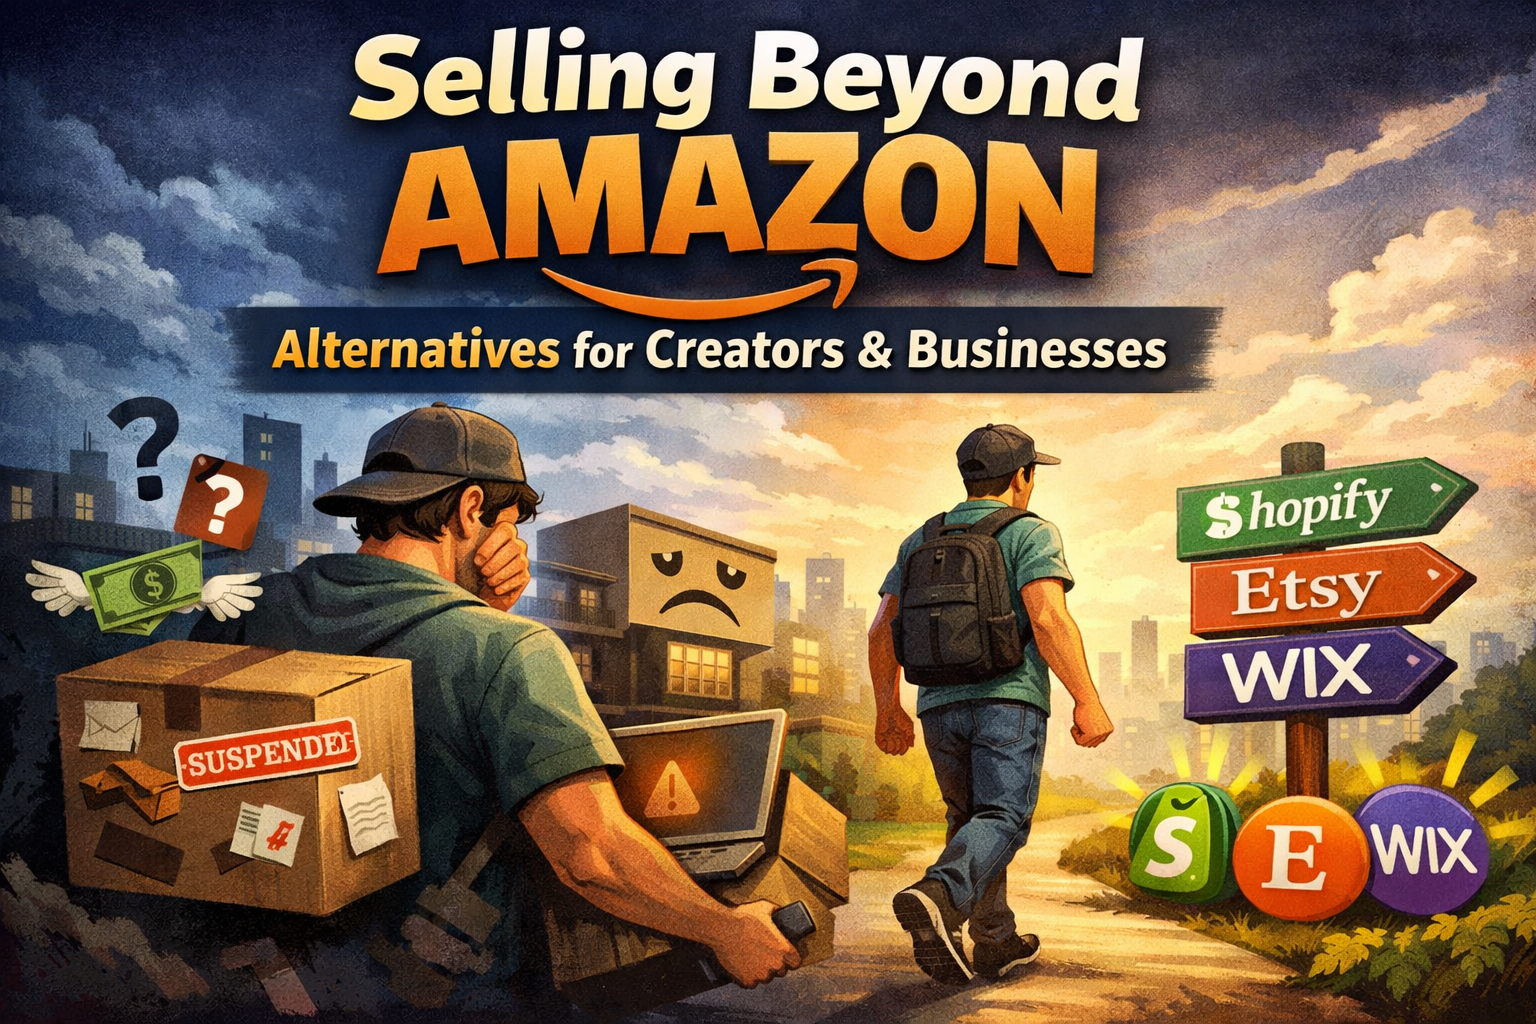
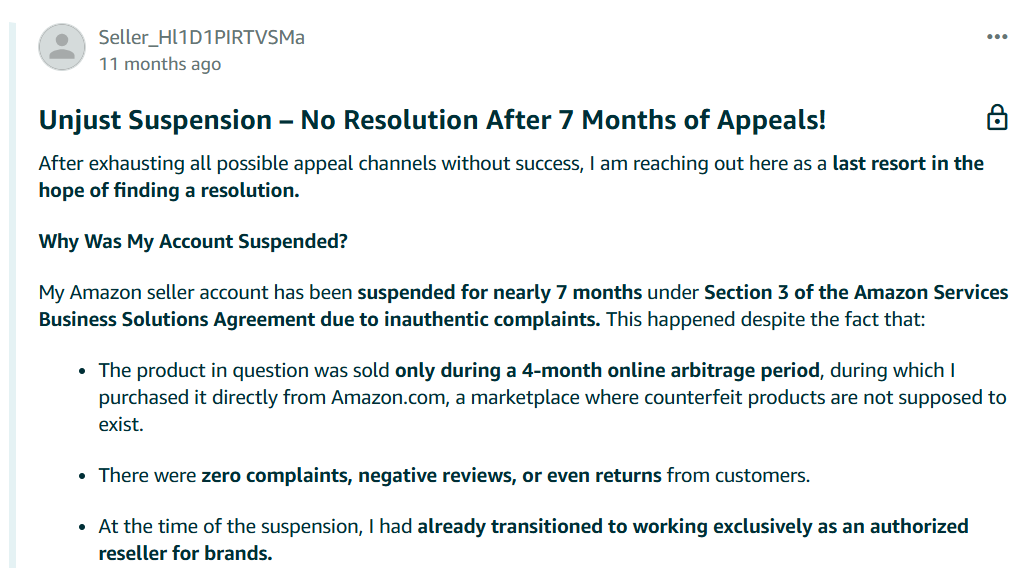
Amazon is the world’s biggest online marketplace, but it still has its flaws. Many creators, entrepreneurs, and small businesses face high fees, intense competition, account restrictions, and limited control over their brand and order fulfilment.

If you have ever used Amazon, you probably know it comes with some regulatory challenges. Sometimes, these issues are hard to understand or explain. I used to sell on Amazon, and it took me over two months to get my first sales processed. When I finally got paid, Amazon had taken almost half of the money. By the time I received my payment, I had lost a lot to various fees, especially since I was not selling in the US.

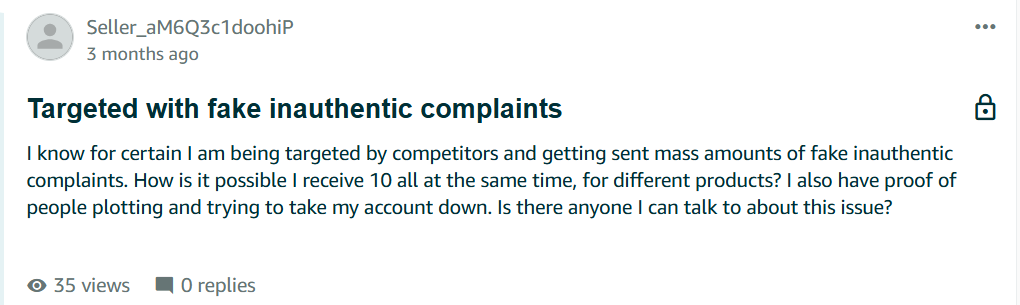
Here are some pictures from other sellers who also could not figure out why their accounts were terminated.

Targeted with fake inauthentic complaints

Unjust Suspension – No Resolution After 7 Months of Appeals!

Focus Is the New Currency in 2026: How to Optimise What isn’t Working and When to Walk Away

How to Optimise What isn't Working and When to Walk Away

Not everything that isn’t working deserves to be abandoned. And not everything that appears to be providing results should be preserved. One of the most difficult focal selections in 2026 will be determining what needs to be optimised and what needs to be eliminated. Many people either quit too soon or stay too long, both of which stifle advancement. Why? Because focus is more than just persistence; it is also about judgment.

In Part 1 of this series, we established a hard truth: in 2026, focus is no longer optional. With rising noise, shrinking attention spans, and endless opportunities, only those who learn to prioritise what truly matters will experience meaningful progress.

Focus Is the New Currency in 2026: How to Win by Doing Less but Better

In Part 2, we went a step further. We confronted one of the most dangerous illusions of productivity—effort without results. We saw why tracking outcomes rather than busyness is the new standard and why focus must always be measured by results, not merely by exhaustive labour. 

Focus is the New Currency in 2026: Tracking results instead of effort. 

What to do with the things that aren’t working

Focus is the New Currency in 2026: Tracking results instead of effort. 

In Part 1, we went through FOCUS as an essential success key in 2026 and how the Eisenhower Principle might help us distinguish between significance and urgency. But it’s only half the job to know what to concentrate on. The true change occurs when we begin assessing result producing tasks rather than how busy we are.

Many individuals are worn out by working a lot yet accomplishing very little in a society where effort is evident, but effect is not always clear. For this reason, tracking results is the genuine measure of focus, which is the new currency. 

In this second part of the series, we will examine why the mind shift that will determine your success in 2026 is to focus on Result generating efforts rather than general effort.

How to Win by Doing Less: Power of Focus in 2026

The Mindshift that must happen. 

Effort is good, but the result is great. That is the phrase that will keep you working in 2026; avoid the trap of ineffective attempts. Many people have grown accustomed to futile attempts to defend their failure to attain their objectives. By discussing their efforts, they make it impossible for them to assess the situation objectively. Every entrepreneur, leader, or individual seeking extreme success must adopt this mindset.

“Effort is good, but the result is great”

Why Effort Is a Poor Metric in 2026

Effort feels wonderful because it’s obvious. You can see yourself working. Others can observe you working. It creates the illusion of momentum. However, hard work alone does not always lead to results.

In 2026, technologies like AI, automation, and other digital leverage will enable ten minutes of focused action to outperform ten hours of fragmented labour. People who understand leverage consistently surpass those who merely understand hard labour. This is why simply assessing effort is problematic. It rewards motion rather than direction. It keeps you occupied without making you productive.

The actual question is no longer, “How hard did I work?”

The question is: “What changed because I worked?”

Results are honest. They reveal what works and doesn’t. They remove emotional attachment to activities and force you to confront reality. When you track results, you start to notice patterns: Which behaviours cause growth?

Results also help you to see which habits contribute to momentum, and which tasks consume time without providing value. Clear feedback improves focus. Instead of guessing, you begin making informed selections. You stop romanticising the effort and start pursuing outcomes. This move alone has the potential to transform productivity, income, creativity, and peace of mind.

Page 1 of 10

Theme by Anders Norén & Customized by Karol K