Putting $1,000 into the stock market and leaving it for 20 years might sound like an easy way to get rich. But is simply buying a stock enough? Imagine you’re 18, starting college in 2006, and instead of spending your $1,000, you invest it in the stock market.
Life moves on. You graduate, start your first job, move, get married, maybe buy a house and have kids. You hardly remember that first investment. Twenty years later, you check your account and think, “Wait. That’s all?”
You might wonder if you should have spent that $1,000 on vacations, dinners, or gadgets. But the real question is: What actually happens when you invest $1,000 in stocks and leave it for 20 years? The answer reveals a key lesson in personal finance:
When you buy shares of a publicly traded company, you become a partial owner of that business.
Your investment can generally generate returns in two ways:
Capital appreciation: Your shares increase in value.
Dividends: The company distributes part of its earnings to shareholders.
But many investors miss something: how much money you actually put in over time. Say you invest $1,000 and get 20 shares. Twenty years later, you still have 20 shares. The company might have grown, with higher revenue, profits, and stock price. But you don’t get more shares just because the company did well. Your investment might grow a lot, but it may not change your life. That’s an important difference.
Why $1,000 isn’t necessarily enough to make you rich
Let’s say two college students, Alex and Jordan, each have $1,000 to invest. Alex invests the entire $1,000 and never contributes another dollar. Jordan also invests $1,000, then adds another $100 every month. After 20 years, Jordan has contributed:
1,000+\(100 × 240 months) = $25,000
That’s $25,000 of contributions before accounting for investment gains or losses. Alex has contributed $1,000. That’s $25,000 put in before any gains or losses. Alex only added $1,000, while Jordan put in 25 times more. So, comparing their final account balances doesn’t just show who picked the better stock. They used different strategies. This is a common mistake for new investors. How long they will stay invested.
The power of investing every month
This is why regular investing matters. Imagine you put in $500 every month. You don’t try to guess if the market will rise next week or wait for the perfect crash. You just stick to your plan. Some months, prices are high. Other months, they’re lower. When prices drop, your $500 buys more shares.
When prices are higher, you get fewer shares. This method is called dollar-cost averaging. FINRA says dollar-cost averaging means investing the same amount at regular times, no matter what the market is doing. It helps you stay disciplined, but it doesn’t guarantee profits or protect against losses.
And there’s an important caveat:
Dollar-cost averaging is not a magic formula.
It doesn’t guarantee your investments will make money or protect you from losses if a stock drops. If you already have a lot of cash to invest, spreading it out over time could mean lower returns if the market rises while some of your money waits. The main benefit is building discipline and staying liquid enough to take advantage of the market’s volatility.
Imagine buying shares in a Nigerian company as a university student, forgetting about the investment for almost 20 years, then checking your account only to find your ₦9,000 investment is now worth around ₦9,900. You would probably feel cheated, right?
That is exactly the kind of story that can make someone question the entire idea of investing in shares.
A woman recently shared on X about how her husband bought Transcorp shares with ₦9,000 when he was a first-year university student about 20 years ago. When he checked the investment years later, he reportedly found that it was worth only about ₦9,900.
His reaction was understandable: he wished he had used the money to buy beer instead. But this story hides a much bigger financial lesson. The question is not simply, “Why didn’t the shares make him rich?”
The better question is:
What actually happens when you buy shares in a company, hold them for decades, and do nothing else?
To answer this lady’s ponderings, we will use Transnational Corporation Plc, commonly known as Transcorp Group, as an interesting case study.
What happened to Transcorp over the past 20 years?
Transcorp was listed on the Nigerian Stock Exchange in November 2006. According to contemporary reporting, the company listed 18.553 billion shares at ₦6 per share. On its first day of trading, strong demand pushed the closing price to ₦6.30.
At first glance, this seems impressive. A share that traded around ₦6 in 2006 is now around ₦36. That is almost a sixfold increase in the quoted share price. I know you have started calculating what it would have cost to buy ₦10 million worth of shares; that would be about ₦60 million today, right?
But this is where the story gets more complicated, and your excitement might suddenly plummet. You cannot simply compare the ₦6 price from 2006 with today’s ₦36 price and calculate an investor’s actual return.
Why? Because Transcorp has changed its share structure over the years.
You might feel like ₦10,000 is too little to start investing. In today’s Nigeria, it doesn’t go far and can be gone after just a few market trips. Sometimes, you might spend it without even noticing where it went.
But there’s another way to see ₦10,000. It can start an investment habit, which is often more important than the amount itself. Many beginners wait until they have a lot of money before learning about investing, but you don’t need millions to build good financial habits. What matters is having a clear goal, choosing the right investment, and staying disciplined about adding more money over time.
So, if you have ₦10,000 right now, what can you do with it? Here’s a simple breakdown.
Is ₦10,000 Enough to Start Investing?
Yes, ₦10,000 is enough to get started. But don’t expect to turn it into ₦1,000,000 overnight. Hoping for quick gains can push you into risky situations or lead you to scams and unrealistic promises.
Instead, see your first ₦10,000 as seed money. Use it to learn how investing works and to build the habit of making your money work for you. The Nigerian Securities and Exchange Commission points to options like equities, fixed-income investments, mutual funds, exchange-traded funds, and real estate investment trusts. The best choice depends on your goals, how long you want to invest, and how much risk you’re comfortable with.
Before Investing Your ₦10,000, Ask Yourself One Question
What do I want this money to achieve?
This question matters more than picking an investment app. Before you invest, know why you’re setting the money aside. Maybe you want to build wealth over time, save for a business, avoid spending it on little things, learn about investing, build an emergency fund, or prepare for a big expense later.
Your answer will help you decide where to put the money. If you need the money next month, you’ll invest differently than someone saving for ten years. Always match your investment choice to your goal and how long you can leave the money invested.
Option 1: Start With a Money Market Fund
If you want a safer place to start, look into money market funds. These funds usually invest in short-term options, and the SEC says they focus on keeping your money safe, earning some income, and letting you access your cash easily. This differs from leaving your money in a regular account.
But remember, not all money market funds are the same. Before you invest, check what the fund aims to do, its fees, risks, minimum amount needed, and how you can withdraw your money. Also, make sure the provider is registered. The SEC has tools to help you check if an investment company is properly registered.
Option 2: Explore Fixed-Income Investments
Another option is fixed income. These investments include government or corporate bonds. Basically, you lend your money and get paid back with some interest, based on the terms of the investment.
The SEC says fixed-income investments usually have less risk than stocks, but the real risk depends on the specific investment. For beginners, the key is this: don’t invest just because someone calls it “safe.”
Make sure you know what you’re buying, who will pay you back, when you can get your money, and what could go wrong. Don’t let the word “safe” take the place of doing your own research.
Have you ever had a product idea and wondered whether people would actually buy it? Many entrepreneurs rush from an exciting idea straight into production. They spend money on materials, packaging, branding and marketing before finding out whether the product is worth developing in the first place.
A great product idea is only the start. Turning that idea into something customers will buy requires careful planning, testing, and smart choices. You need to know your customers, research the competition, consider costs, develop the product, and see how people react before fully committing.
This is where product planning matters. Product planning means coming up with new product ideas, evaluating them, turning the best ones into real products, and then bringing them to market. It also means improving current products and stopping products that no longer make money.
If you are an entrepreneur planning to develop a new product, these 9 steps can help you move from an idea to a market-ready product.
1. Start With More Than One Product Idea
The first step is coming up with ideas. Instead of putting all your time and money into the first idea you think of, gather a list of possible product ideas.
Your ideas can come from many places. You might spot an opportunity through your own experience, customer complaints, conversations with current customers, competitors, workers, suppliers, or industry groups. Research groups and other experts can also give ideas.
The goal is to generate options, not make a final choice. An entrepreneur with several ideas has more choices to consider before picking the product worth serious investment.
For example, imagine you want to build a business around healthy snacks. You could consider producing granola, dried fruit packs, protein snacks or a local healthy snack alternative. Rather than immediately producing thousands of units, you can first consider which opportunity has the strongest potential.
Don’t spend money making the product before you have taken time to study the idea.
Having several ideas is helpful, but you can’t work on all of them. The next step is to filter your ideas and keep only those that deserve more focus. Ask practical business questions. How much demand could the product have? Who are the competitors? Can you obtain the raw materials needed to produce it? Is the expected sales volume attractive enough to justify the investment?
The goal is to avoid making an expensive decision just because you are excited. Some ideas may seem great but turn out to be hard or costly when you look at the market and needed resources.
At this stage, you are not trying to prove that your idea is perfect. You are trying to determine whether it deserves the time, money and resources required for further development. Also Read:Maximising Business Decision-Making Using AI
3. Turn the Idea Into Something Customers Can Understand
Once an idea survives screening, it needs to become more specific. This is the concept development and testing stage.
There is an important difference between having a product idea and having a clear product concept. An idea is a possible product, while a concept makes it more detailed and easier for the business and customers to understand. At this point, you are building a product image, which refers to the personal impression customers have of the product.
You should also be able to explain what the product is, what it does and why someone would want it. You can then test the concept using descriptions, pictures or other ways of presenting the proposed product to potential consumers.
The goal is to see how people respond to the concept and if the idea needs changes. You also want to find out who is most likely to buy the product.
This can help an entrepreneur avoid a common mistake: making a product based only on personal guesses about what customers want.
Are your employees constantly missing deadlines? The problem may not be laziness. Poor communication and a lack of trust could be affecting your team’s performance.
A business can have talented employees and still struggle to get work done on time. Projects get delayed. Customers become frustrated. Managers spend more time following up. Employees blame one another, and the same problems keep happening.
One common reason is poor communication in the workplace.
This issue was a major assignment in one of my MBA classes: how do we fix communication issues as a manager? The question was simple:
Imagine you are a manager, and your team is missing deadlines because employees are not communicating well with each other. What is the main problem, and what steps would you take to solve it?
At first, the obvious answer might be poor communication. However, poor communication can be a symptom of a deeper problem and in many teams, that deeper problem is a lack of trust.
Why Are Employees Missing Deadlines?
Missing a deadline does not always indicate that an employee is irresponsible. Often, an employee may lack the necessary information to complete the task, misunderstand another team member’s expectations, notice a problem but hesitate to report it, or assume someone else is handling part of the work. Therefore, managers should look beyond the missed deadline and ask the right questions to understand the underlying reasons.
The big question a manager should ask is this: Why did the communication fail?
Several factors can contribute to poor communication within a team, and in today’s article, I will help you identify 5 major causes of poor communication in the workplace and how to address each one.
5 Major Causes of Poor Communication in the Workplace
1. Lack of Clarity
Employees need to understand what they are expected to do. Without clarity, communication is ineffective. Clarity is not what you think you said; it is rather what the person understands you to have said. That means you might need to be more specific about what you are trying to communicate, especially when you are working with a team that is not used to seeing your work.
If a manager says, “Get this done quickly,” different employees may interpret “quickly” differently.
A good manager should clearly communicate:
What needs to be done
Who is responsible
When it should be completed
What standard is expected
What resources are available
Clear expectations reduce unnecessary confusion.
2. Poor Listening Skills
Communication is not only about speaking; it is also about listening. An employee may receive instructions but fail to understand them because they were distracted or did not ask questions. That is why every manager must be patient enough to troubleshoot conversations with their staff. Encourage them to give instant feedback on what they heard you say.
A simple question such as “Can you repeat what you understand the task to be?” can prevent major mistakes.
3. Lack of confidence.
This is where the situation worsens. Employees who do not trust their management or coworkers may be more reluctant to speak out or share information. For example, an employee may see that a project will miss its deadline.
Instead of informing the management, the employee may remain silent because they are terrified of being chastised.
By the time the manager finds out, it may be too late to solve the situation. Trust allows workers to say things like:
“I have difficulty with this work. “I need help.” This type of talk may rescue a project.
4. Inappropriate Communication Channels
Not every message should be communicated through the same channel.
Some businesses depend heavily on WhatsApp groups. Others use email, Slack, Microsoft Teams, project-management software, or face-to-face meetings.
The problem is not necessarily the platform. What matters is that businesses establish clear communication channels for different types of information.
For example:
Urgent issues → phone call or direct message
Formal instructions → email or documented platform
Team updates → team communication channel
Complex issues → meeting or video call
Also, I see some businesses with a mandatory rule that staff must communicate only through certain platforms. While this is necessary in many sensitive departments, for most day-to-day work, managers should encourage direct communication to reduce the bureaucratic feel.
5. Different Communication Styles
Individuals communicate differently. One employee may prefer direct teaching. Another may require further explanation. Some staff talk openly in meetings, while others prefer to share their views discreetly.
Managers must comprehend these distinctions. Good leadership doesn’t require everyone to communicate the same way. It means creating a setting where everyone can communicate successfully.
Nigeria consumes about 2.7 million metric tonnes of palm oil annually but produces only about 1.5 million metric tonnes. This leaves a supply gap of more than one million tonnes annually, requiring over $290 million in palm oil imports in 2024 alone.
Think about this for a moment: A country historically known for palm oil is now spending hundreds of millions of dollars to import a product it can produce itself. In the 1960s, Nigeria controlled almost 40% of the global palm oil market. Today, that figure has dropped to less than 2%, even as local demand from households, food processors, manufacturers, and export markets rises.
The Oil Palm opportunity has not disappeared
Nigeria’s fertile Palm Belt remains naturally suited for oil palm cultivation. The challenge has not been whether the land can produce, but rather issues such as poor seedlings, fragmented farming systems, underinvestment, and limited commercial-scale execution.
For investors, this raises an interesting question:
If Nigeria already has demand, suitable land, and a market that depends heavily on imports, could oil palm become one of the overlooked long-term investment opportunities of this decade?
Whether you live in Nigeria, the UK, Canada, the USA, or elsewhere in the diaspora, there are several ways to gain exposure to the oil palm value chain, from plantations and processing to partnerships and structured agricultural investments.
In this guide, we’ll explore the opportunities, startup costs, timelines, risks, and practical ways to enter Nigeria’s oil palm business wisely.
How to Start Investing in Oil Palm Production
For someone in the UK, Canada, or the United States saying, “I want to invest in oil palm. I have seen the market gap and think I can fill my share of the demand. But where do I start planting?” The answer may be simpler than many imagine.
In fact, it may be simple enough that you do not need to leave your location to participate in oil palm farming in Nigeria.
The standard path many take is to secure land, then hire a local manager to run the farm and send monthly reports. While this can work, it often leads to a steeper path to profitability and sustainability than expected. Managing an agricultural business remotely adds complexity: land verification, staffing, supervision, report quality, operational delays, and decision-making across locations and time zones.
For many diaspora investors, the challenge is not always access to capital; it is access to trusted execution.
That is why another route has increasingly gained attention: rather than building entirely from scratch, some investors choose to work with experienced, government-registered oil palm businesses and operators who already understand cultivation cycles, have existing systems, and know what it takes to run productive operations on the ground.
This does not remove the need for due diligence or eliminate risk, but it can reduce some of the early operational hurdles that discourage people from participating in agriculture from abroad.
How Towers Palm is Changing the Oil Palm Investment Space
Most creators don’t fail because they lack talent; they don’t fail because they don’t have the latest gadgets to produce with. They fail because they spread themselves too thin. Trying to do many things at the same time. One week, they are making business content. Next week, they are posting comedy. Then motivation, finance, worship, lifestyle, and five other ideas at once. In today’s blog, I will show you a straightforward way to build unstoppable momentum as a content creator.
Momentum is difficult to build when your energy is divided. If you want to grow as a content creator, there are four principles that matter more than fancy cameras, expensive courses, or secret algorithms. These four secrets I am about to share with you are just the recipe that have been proven by global creators, and they can change your life in a moment.
1. Pick a Niche, but Don’t Pick What You Merely Like
A common mistake creators make is choosing a niche based solely on passion. Content should solve problems for your audience, even when you are not present. While passion is important, expertise significantly enhances its impact.
The best niche usually sits at the intersection of three things:
What you can talk about for years
What experience, training, or certification do you have
What produces value for other people
You do not need a PhD to teach online. However, if you have spent years studying, practising, working, serving, building, researching, or creating in a field, this experience gives you a significant advantage. Your experience reduces the learning curve for your audience.
As a creator and entrepreneur, Gary Vaynerchuk often emphasises:
“Document, don’t create.”
Meaning: start from what you already know.
Your niche should not feel like acting. It should feel like speaking from accumulated understanding. That is why you must choose a niche where your expertise is recognised and respected, and where you feel free to express yourself.
If you think you need tens of thousands of dollars before you can start investing seriously, you are making a big mistake. The truth is that many successful investors built their wealth one small investment at a time, with as little as 1,000 dollars. If you’ve managed to save your first $1,000, you’re already ahead of millions of people who are still living paycheck to paycheck.
The question now is not whether you should invest your money, but how to invest it wisely.
Shalom
In 2026, investors will have more opportunities than ever before. From stock market index funds and dividend-paying companies to real estate investments and online businesses, a thousand dollars can be the beginning of a powerful wealth-building journey.
This guide will show you the best ways to invest $1,000, the risks involved, and how beginners can create a simple investment strategy that works.
Why $1,000 Is a Great Investment Starting Point
A thousand dollars may not seem life-changing, but it represents something more important than the money itself: financial momentum.
When you invest your first $1,000, you begin developing habits that can help you build wealth for decades. That habit is the key to success, and one way it helps you flourish is by making you feel like an achiever and propelling you to do more. Also, when you begin to invest, you begin to understand a number of success principles as you learn:
How investing works
How to manage risk
How markets behave
How compound growth builds wealth over time
The goal of this investment is not to double your money overnight. The goal is to create a system that allows your investments to grow consistently year after year. Are there investments that can probably double your income in a day? Yes, however, it’s too risky to build a long-term wealth system, so in today’s investment lesson, we are looking at the steadily growing investment structure.
Before You Invest: Build a Financial Foundation
Before investing your $1,000, make sure you have an emergency fund so that you don’t have to sell off your investment abruptly when unexpected needs arise. Car repairs, medical bills, job loss, and home repairs can force you to sell investments at the wrong time. In practical terms, aim to keep at least 3 to 6 months of living expenses in an emergency fund.
Another helpful thing to do might be to get high-Interest debt under control; If you’re paying 20% interest on credit card debt, paying it down may provide a better return than investing. Reducing expensive debt can be one of the smartest financial decisions you can make.
To set a clear financial vision, you can ask yourself:
Are you investing for retirement?
Building passive income?
Saving for a home?
Creating long-term wealth?
Your goals should influence your investment choices.
Best Ways to Invest $1,000 in 2026
1. Invest 1000 dollars in a Friends Business
You must have heard people say things like, “Someone invested in Uber in its early days and is now a millionaire.” If you invested $1,000 in Uber in its first round, your investment would be worth about $5 million at its peak.
Many people don’t appreciate the power of strategic friendships and connections in their lives. If you have a friend or family member who is ambitious and has integrity, there is nothing wrong with structuring a legally binding deal.
The only caveat is to do something that is structured so that you don’t have to get into issues that affect the relationship you share later in the future. The advantage of investing in friends and family is that you often get to be a part of what they are doing, and this also allows you to get a premium at a more affordable price than you would normally get.
2. Invest 1000 dollars in an S&P 500 Index Fund
For many beginners, this is one of the simplest and most effective options. An S&P 500 index fund gives you ownership in hundreds of America’s largest companies through a single investment.
Benefits include:
Instant diversification
Low fees
Strong long-term performance
Minimal maintenance
The S&P 500 has shown strong long-term growth and is one of the most popular indices for tracking the stock market. Over the past 100 years (as of February 2026), it averaged a 10.424% annual return with dividends reinvested. After adjusting for inflation, the return was 7.268%, indicating that much of the growth kept pace with rising prices.
In shorter time frames, the results were also solid: the last 50 years saw an average annual return of 11.71% (7.84% after inflation), the last 30 years returned 10.121% per year (7.431% after inflation), and the last 20 years averaged 11.844% (8.146% after inflation). The past 10 years were especially strong, with an average annual return of 15.62%, or 12.022% after inflation. Dividends made up about 30% of total returns during these periods.
Looking at the S&P 500’s history, long-term investors who stayed patient and reinvested their earnings have usually done well. Even though annual returns can fluctuate due to economic conditions, inflation, or market events, the overall trend shows that sticking with it over time has helped people build wealth and beat inflation.
A lot of people think they need thousands of dollars to begin investing. In reality, many of the world’s most successful investors began with small amounts, such as $100. They built their wealth by making investing a regular habit, even before they had much money.
Today in America, $100 might not feel like a lot. It could pay for groceries, a streaming service, or a tank of gas. But if you invest that $100 wisely and keep at it, it can help you build long-term financial growth.
Inflation is a big challenge for Americans right now. Prices for housing, healthcare, groceries, and transportation keep rising each year. Even though a savings account feels safe, inflation slowly erodes the value of your money.
Because of this, many people are asking an important question:
How do I stop simply saving money and start growing it?
Sadly, many new investors have had bad experiences. Some bought into investments that were all hype and then lost money. Others followed social media trends without knowing the risks. Some just left their money sitting and watched inflation slowly erode its value.
The good news is that investing isn’t gambling if you have knowledge and discipline. With a smart plan, $100 can be the first step toward building wealth, earning passive income, and reaching long-term financial security.r some of the best investments you can start with $100 in 2026, including their risks, potential rewards, and beginner-friendly platforms to help you get started.
Why Keeping Your Money in a Savings Account May Not Be Enough
Many Americans still keep most of their money in regular savings accounts. These accounts are good for emergencies and short-term needs, but they aren’t meant to help you build real wealth.
For example, if your savings account pays 1% interest each year but inflation is 3%, your money is actually losing value, even if the balance goes up a little.
For example, if you leave $100 in your account for a few years, it might buy less in the future than it does now. That’s why many financial experts suggest investing some of your money instead of keeping it in savings accounts. Letting money work for you instead of sitting idle, your capital can generate returns through interest, dividends, business growth, or appreciation.
But before you invest, it’s important to know why some people lose money in the market.
I grew up in one of my grandfather’s properties. He built several houses, and many of his children inherited them. My dad once told me that the ₦25,000 paid to the contractor to start one of those projects was physically carried on his head in a sack when they wanted to pay. Today, ₦100,000 hardly feels enough for transportation and monthly expenses for many Nigerians. Yet with the right investment structure and consistency, that same ₦100,000 can be the start of financial freedom.
Many young Nigerians are asking an important question: ‘How do I stop merely spending money and start growing it?’ But there is another problem. People are tired of hearing investment stories because many have already been burned. Some invested in apps that crashed. Others locked money in platforms that suddenly stopped paying. Some even watched inflation quietly reduce the value of their savings while the money sat in their bank account doing nothing.
In short, for many people, investing is more like a second term for losing money and honestly? Their fear makes sense. However, the good news is this: Investment is not gambling when you understand what you are doing. With the right knowledge, ₦100,000 can become more than emergency money. It can serve as a starting point for wealth creation, passive income, business ownership, digital investing, and long-term financial stability.
In this guide, I will show you realistic investment opportunities in Nigeria you can start with ₦100,000, including the risks involved, expected returns, and platforms beginners can use safely.”
Savings or Shavings Account
If you put 100,000 naira in a savings account today, just being credited that 100,000 in Nigeria means you will lose #50 instantly. That is, if your bank is not immediately billing you for any other monthly maintenance fees. It’s not their fault entirely, too, because when you think about the fact that the bank has to make money one way or the other, or how do they make money if they are only keeping your money for you?
What about the effect of Inflation on the Naira? As of April 2026, Nigeria’s headline inflation rate stands at 15.69%, based on the latest report from the National Bureau of Statistics (NBS). This is up from 15.38% in March 2026.
Put simply, prices for goods and services in Nigeria keep rising, while the value of money is slowly declining. For example, if something used to cost ₦10,000, it might now cost ₦11,500 or even more. This also means that if you leave your money sitting without investing or growing it, its value will slowly decrease. Inflation has raised the overall cost of living, putting more pressure on salaries and incomes.
To put it simply, ₦100,000 today does not buy as much as it did a few years ago. This is why many people are now searching for better ways to grow their money rather than just saving it. Investing helps you take your capital, which is like a seed, so that it can produce other seeds that can all grow to become a massive wealth estate for you financially.
But before you invest one naira, there is something you must understand, which is why Nigerians lose a lot of money to wrong investments.
“I have invested in banks and other apps, but they eat my money.”
Mr David speaks for many new investors who have lost money to scammers or been let down by broken promises. First, saving in a bank is not the same as investing. Saving helps the bank more than it helps you. You should not expect to get rich by saving money in the bank. If you feel let down after saving for a long time, your expectations may have been unrealistic.
Firstly, Banks are built to avoid risk. Even if they take risks, they do it quietly and make sure they are protected. Because banks avoid risk, you cannot expect high returns from saving with them. Low risk means low rewards. If you want to save before investing, a bank is a good place to start, but not the best place to grow your money.
Luckily, Cowrywise and other investment apps now let you invest with as little as 1,000 naira in very juicy investment offers. Click my referral link to get instant entry, and you can start your investing journey without saving large amounts: https://get.cowrywise.com/r/Oluwawyi
The second reason I think many people have been disappointed with many investments is the Return on Investment narrative. Risk is calculable, but what of uncertainty? Many investments are victims of uncertainties, I mean events that they didn’t even see coming at all. If anyone tells you their investment is not prone to risk at all, then it is either that they are lying to deceive you or they have a solid insurance structure that cushions their losses. In fact, the first way to identify a scam opportunity is when they sell something that is 100% risk-free. The financial world does not exist without risk and uncertainties, and not being aware of the risk to reward ration on your investment can be the greatest undoing of your investment ambition.
Having said this, I would go ahead and quickly show you how to recognise a legitimate investment from one that is not.
What Makes an Investment Legit?
When you are looking to know the legitimacy of an investment, a number of things stand out, and if you carefully examine all of these, it’s almost impossible to lose your money in the process.
Founders This is simple. Are the founders traceable to any prior failed projects? If yes, then that is a big red flag. If you can’t find the founders, check the company’s history. Have they raised any capital from reputable venture firms or angel investors before? If they have, then they are most certainly legitimate.
Registered company The Security and Exchange Commission (SEC), Nigerian Investment Promotion Commission (NIPC) and the Central Bank of Nigeria (CBN) regulate investment firms in Nigeria, where applicable. If your investment broker is not regulated by any of these regulators, I can assure you that you will soon be crying with regret over losing your hard-earned money. A simple Google search or prompt on ChatGPT can save you from a whole lot of issues in the future.
Clear business model An investment bank or broker makes money from commissions or by investing or doing business with capital, not primarily through a multilevel referral scheme. If you have to refer someone to keep your investment scaling, you are not investing; you are likely in a Ponzi scheme. The best way to avoid this is to not start at all.
Transparent returns Realistic promises are the only thing that works; if you are getting unrealistic promises from your broker or investment firm, you should be assured that you will lose your money. It’s not bad to take risks, but if you can’t afford to lose it, don’t trade with it. If losing an amount ends your financial journey, you should either be saving or investing in a simple, safe, and steady investment mix that preserves your capital with little return.
Withdrawal history Withdrawals are what guarantee that your investment worked. Make sure you read your broker’s terms and conditions, especially those related to withdrawals, before you invest. I know a friend whose parents invested in Ethereum in its early days, but the broker didn’t give them keys or the wallet. Now they don’t even know how to access the investment or the person who invested on their behalf.
User reviews This is where the rubber meets the road. If you can find a real review from a real user and not a user-generated content that was farmed, then you might just be able to honestly predict the reality of investing with that broker or investment firm. Try going through reviews on the Google Play Store and Apple App Store, if they have mobile apps, to see what people who really use the app think.
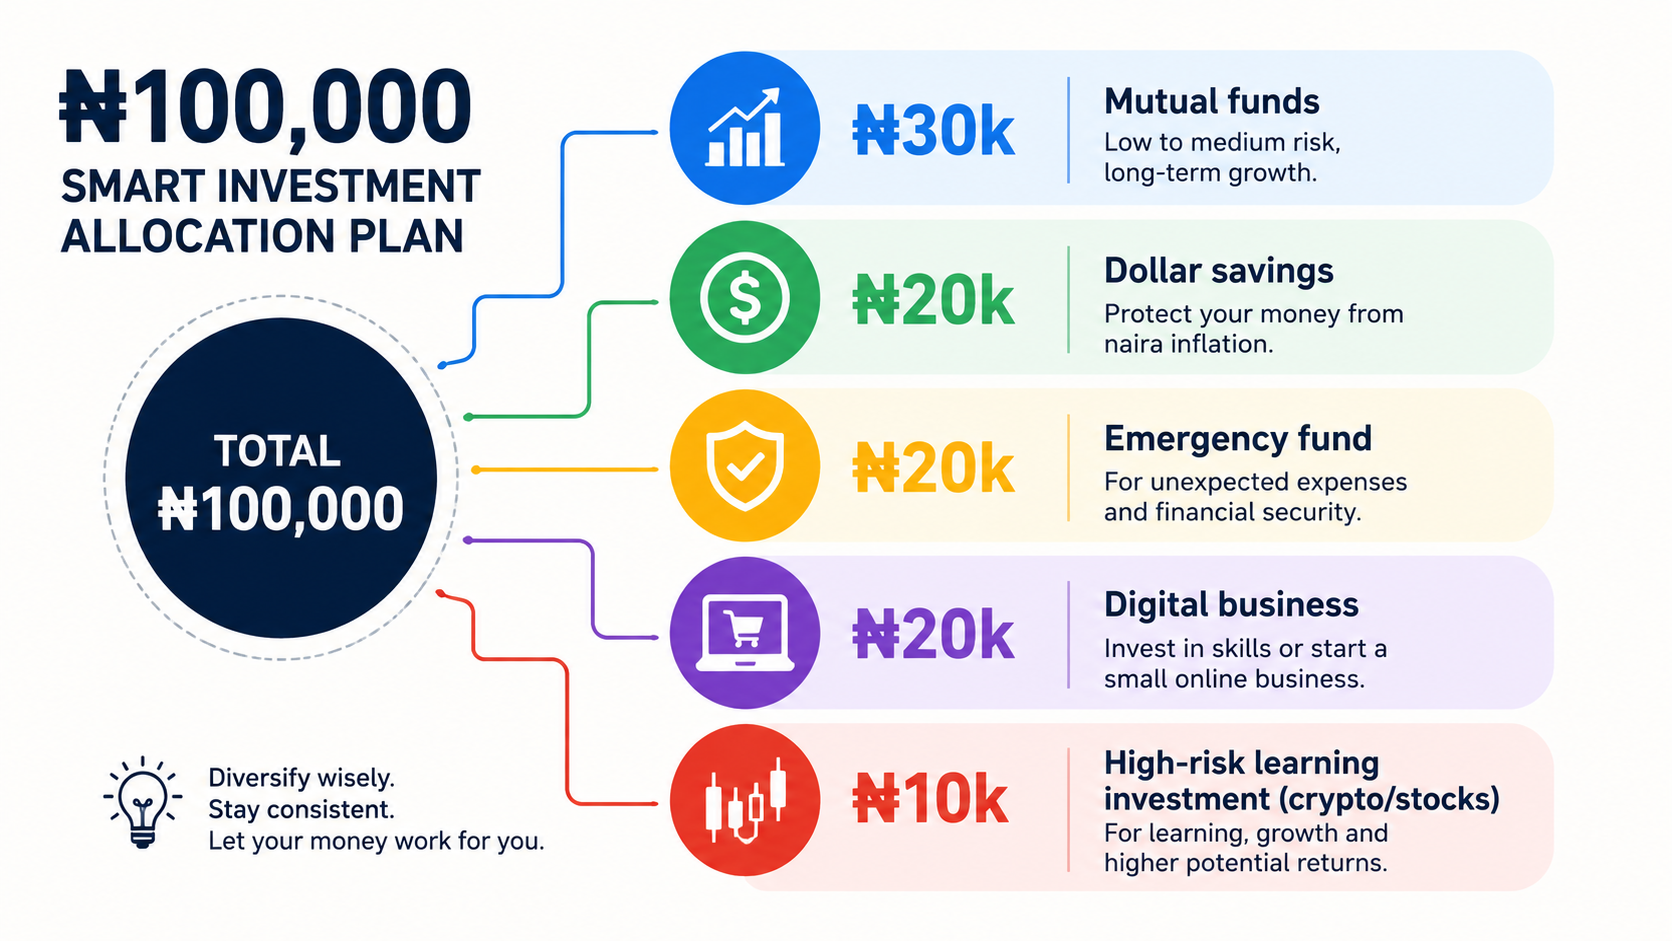
Investment Mixes You Can Start with ₦100,000
A. Treasury Bills & Fixed Income Treasury bills and other fixed-income investments are considered low risk because they are backed by the government or major financial institutions. Your money is usually safe, so these options work well for anyone who wants to avoid losses.
These investments are great for beginners. You do not need advanced financial knowledge or much effort to manage them, so new investors can start growing their money without much stress. Fixed-income investments give you steady and predictable returns. You can usually tell how much interest you will earn, which helps you plan your finances more easily.
B. Mutual Funds Mutual funds are run by experienced professionals who pick investments for you. This way, you can benefit from their expertise without spending time analysing individual stocks or bonds yourself. One of the main benefits of mutual funds is diversification. Your money is spread across many investments, so you are less likely to lose everything if one investment does poorly. A convenient choice for people with busy schedules. Since a professional manager handles all the investment decisions, you can invest without constantly monitoring the market.
C. Agric Investment Platforms Agric investmeAgric investment platforms are riskier because they depend on things like weather, crop yields, and market prices, which can change unexpectedly. The rewards can be good, but there is also a higher chance of losing money than with safer investments. It is better to approach agric investments with caution. Always do your research, understand the risks involved, and avoid investing more money than you can afford to lose.
D. Nigerian Company stocks
When you invest in Nigerian stocks, you own shares in local companies. This lets you benefit from the country’s economic growth and earn money through dividends and rising share prices.tal gains.
Dividend investing means choosing stocks that pay regular dividends to shareholders. This gives you a steady income, plus any gains if the stock price rises. When investing in stocks, it is crucial to think long-term. Prices can rise and fall in the short term, but staying invested for years usually gives you a better chance of good returns. Certificates help protect your wealth from the effects of naira inflation. By holding assets in a stable foreign currency, your money is less likely to lose value over time due to local currency fluctuations.
You can use options like Eurobonds or dollar savings accounts to invest and save in US dollars or other stable currencies. These choices can deliver good returns while reducing the risk of local currency depreciation.
F. Cryptocurrency Cryptocurrency investments are very risky but can also yield high returns. Prices can change a lot in a short time, so you might make big profits or face large losses quickly. In cryptocurrency, it is essential to educate yourself about how it works. Understanding the technology, the risks, and the market trends can help you make informed decisions and avoid costly mistakes.
Avoid investing in so-called ‘hype coins’ or cryptocurrencies that are heavily promoted but lack strong fundamentals. Stick to established coins and always research before investing any money.l Business
G. Start a Business online
Starting a small digital business is powerful because it shifts you from a passive investor to an active wealth builder. Running your own business lets you create new income streams and learn valuable skills.
Examples: – Mini importation – Blogging – YouTube – Digital products – Printing business
You can easily share these digital business ideas with others. Sharing real examples and success stories can inspire more people to take action and begin their own business journey.
Mistakes to Avoid When Investing ₦100,000
Chasing investment opportunities that promise very high or unrealistic profits often leads to disappointment or loss, as such deals are usually too good to be true.
Putting all your savings into investments without keeping some cash on hand can leave you at significant financial risk if an emergency arises or your investments don’t perform well.
Not saving money for emergencies before investing can leave you open to unexpected costs and force you to sell your investments when it’s not a good time.
Making investment choices just because of trends or excitement on social media can lead to poor results, since these sources are often unreliable and don’t align with your personal goals.
Neglecting your money without proper research or understanding the risks involved can lead to losses and missed opportunities for more suitable investments.
Final Key on Investing your First #100, 000
₦100,000 may not seem like much today, but many rich people began by learning to handle small amounts carefully. The aim is not to get rich quickly. The aim is to build money smarts, steady habits, and patience. A small investment made carefully is stronger than a large investment made with emotion.